Insurers & Reinsurers
Parametric weather risk from organised smallholder supply chains. We originate, calibrate and administer each programme; you write and carry the risk on terms you can audit.
- Premium collection risk
- Delivering farms per partner
- From trigger to payout
A New Risk Class, Ready to Underwrite
Hundreds of millions of smallholder farms remain uninsured, not for lack of demand, but because distribution, premium collection and data have made the risk uneconomic to write. Each programme solves these three problems before a single policy is issued.
Distribution and Collection Built In
Policies are placed and premiums settled through the delivery points of established offtakers. You carry no sales cost and no premium credit risk.
Data Before Risk
Each programme brings at least three years of delivery histories. Before any risk is written, triggers are frozen and evaluated live through a full shadow season.
Interests Aligned
Interscale's take rate is paid only after claims and programme costs, and is reduced in loss years. We earn from accurate pricing, not from volume.
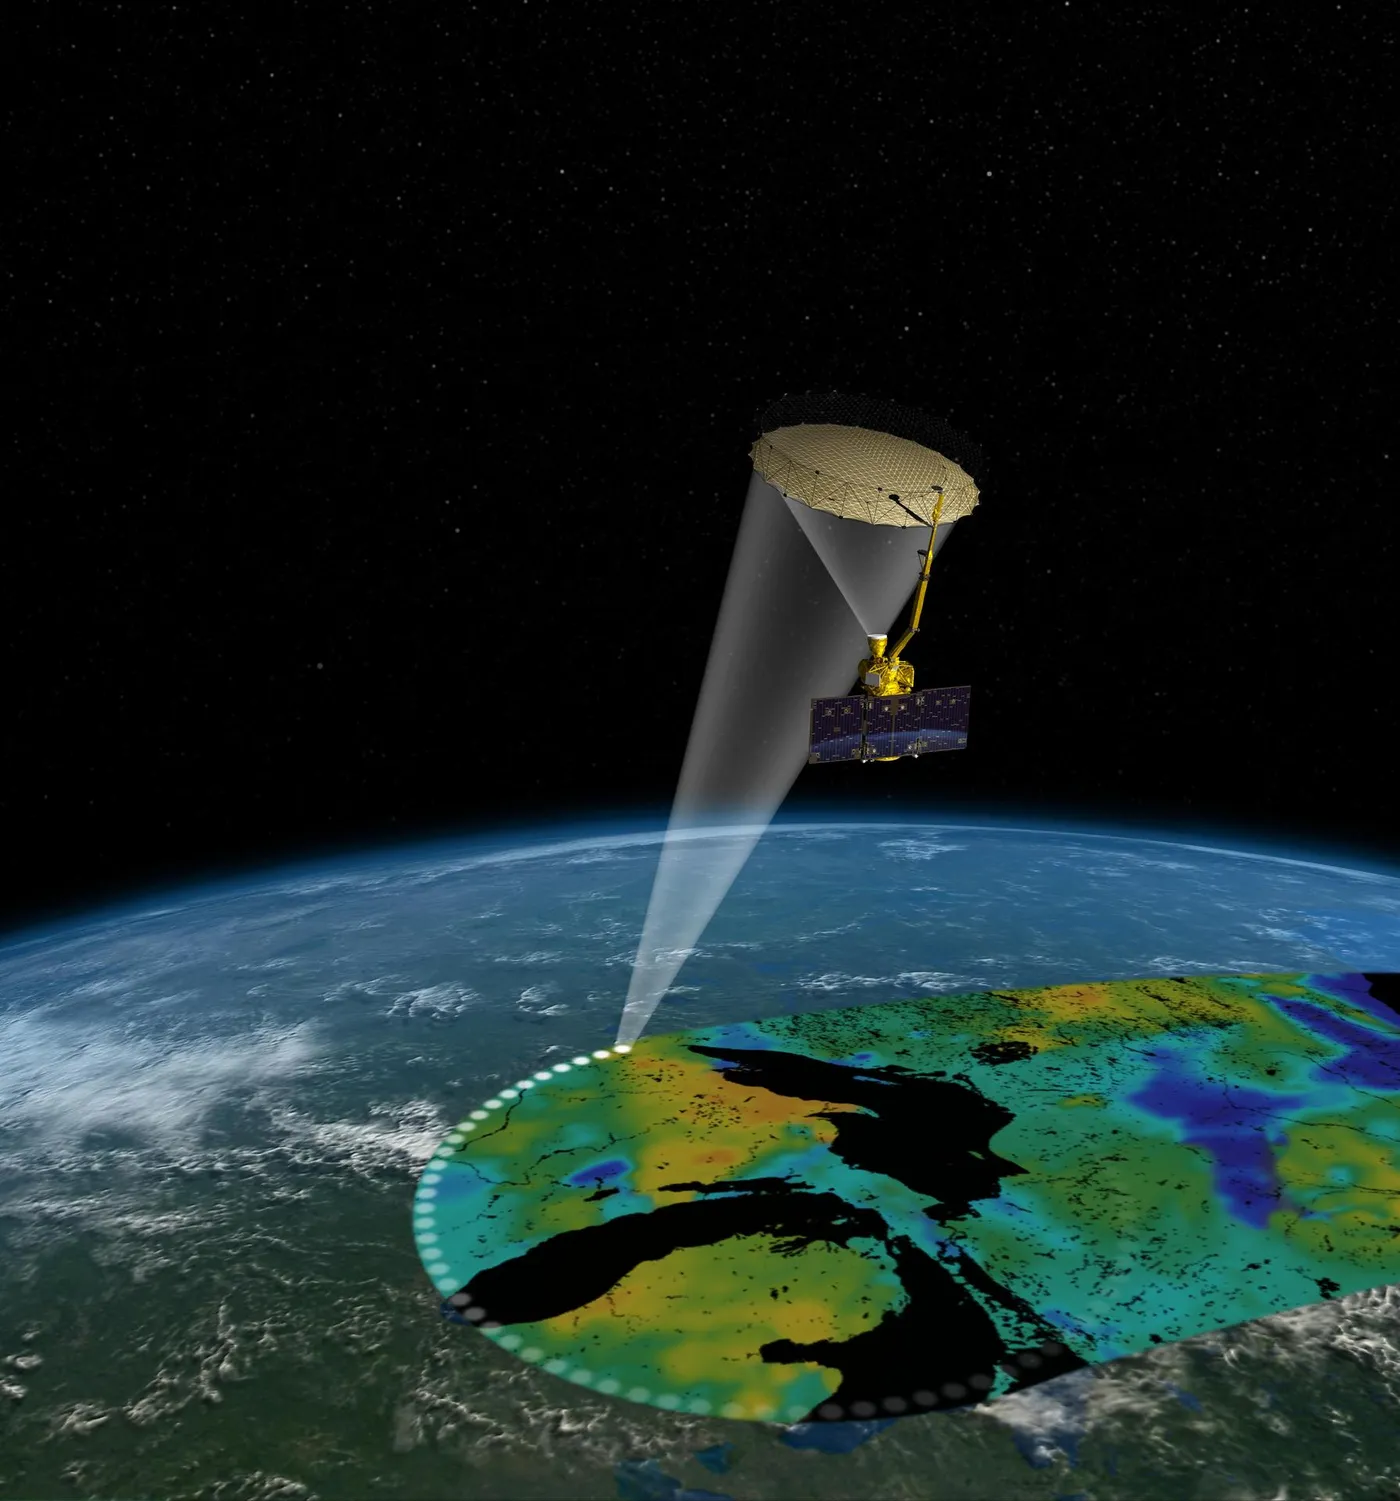
You write the risk, we run the programme.
Interscale handles trigger calibration, the receivables register, payout operations and reporting, so you can focus on underwriting and capacity.
Your Role in a Programme
Two roles, one programme structure, agreed per supply chain and region.
As Fronting Insurer
Issue the Policies
You issue policies under a group framework contract, with the participating farmers as policyholders.
Cede the Risk, Earn a Fee
You cede the risk to reinsurers and earn a fronting fee without distribution effort. You remain the regulated counterpart in the market, with Interscale as your technical service provider.
As Reinsurer
Quota Share
You take a quota share of the programme risk, priced on frozen trigger specifications and published backtests.
Aggregate Stop-Loss
You can also write an annual aggregate stop-loss that protects the programme pool's retention across programmes, regions and seasons.
Fast Payouts, Together
Payout Liquidity
Payout liquidity is agreed with you upfront, so that farmers receive their money within five banking days of a trigger event.
One Verifiable Record
Pledges, payouts and settlements are recorded per farm, season and micro-region in a shared register that you can verify at any time.
Built for Underwriting
Multi-Parameter Indices
Satellite data, modelled soil moisture and weather-station records, calibrated per micro-region against delivery histories.
Frozen, Versioned Triggers
Parameters, thresholds, measurement windows and payout scales are fixed and published before each season, and do not change during it.
Basis Risk on the Table
The backtested false-negative rate is disclosed before you write, so you underwrite the product as it is, not as it is described.
An Auditable Engine
Pricing and trigger evaluation run on a versioned, deterministic engine. Every result can be reproduced and audited.
Diversified by Design
Programmes are selected for weakly correlated perils, non-overlapping season windows and multiple jurisdictions, and correlation is tested against ENSO phases.
Skin in the Game
The programme pool retains a share of every risk it places, so the structure carries a stake in its own results.
Questions and Answers
Who is the policyholder?
The participating farmers, under a group framework contract issued by the fronting insurer. The insurable interest lies clearly with them.
What is covered, and what is not?
Each programme covers the dominant weather peril of its region, such as drought, through a multi-parameter index. Individual losses without a regional weather signal, crop disease, price declines and post-delivery losses are not covered.
How is basis risk measured?
Triggers are backtested over more than 20 years and evaluated live in a shadow season against actual deliveries. The resulting false-negative rate is part of the programme documentation.
Can we audit the engine?
Yes. Trigger specifications, model versions and every evaluation are recorded, so that each payout decision can be reproduced independently.
How do premiums reach the pool before planting?
Farmers pledge a fixed share of their harvest. At the start of the season, these pledges are sold to liquidity partners, so the pool is funded in cash before the risk period begins.
How is the retained risk protected?
The programme pool retains a share of the risk; above a defined threshold, an annual aggregate stop-loss applies. The layering is agreed with the risk partners of each programme.
Other Partners in the Ecosystem
Discuss Programme Capacity
Talk to us about upcoming programmes, our data and our trigger methodology.
Get in Touch